ENTERPRISE SALES / DECEMBER 2025
Hairline Cracks
How hairline cracks in digital banking drive silent attrition and break customer relationships. Dams never fail in one big moment. They fail in thousands of tiny ones.
Enterprise Sales / DECEMBER 17, 2025 / 8 MIN
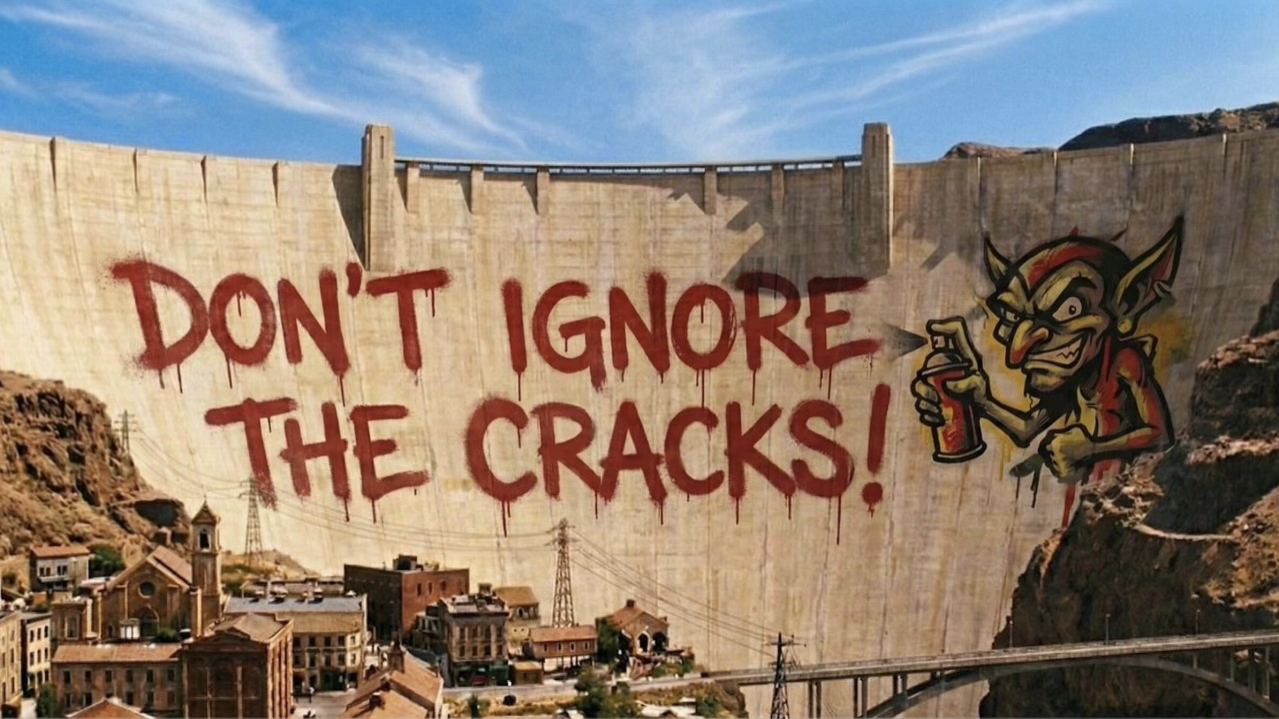
On the edge of a small mountain town stood an old concrete dam. A quiet giant, holding everything together. Schools were built in its shadow. Families picnicked by the reservoir. It was the kind of structure everyone trusted without thinking.
Everyone except one engineer.
Every morning, she walked the base of the dam, scanning the concrete. Not for gaping holes or dramatic failures, but for something far smaller…easier to miss.
Hairline cracks. Faint fractures no wider than a hairline, barely visible unless you were searching for them. A thin line here. A subtle split there. Nothing alarming enough to gather the town council.
Dams never fail in one big moment. They fail in thousands of tiny ones.
One morning, she found a crack slightly longer than before. At its center, a single droplet of water beaded up and slid down the face of the wall. Just a drop. But to her, it meant everything.
The town continued with life as usual… confident, comfortable, completely unaware that the pressure inside the structure had already begun to shift. She whispered to herself: This is how it starts.
Micro-Moments That Compound Into Attrition
In digital banking, hairline cracks are micro-moments of friction that compound into silent attrition. A customer opens their banking app, followed by a brief stall. A spinner that hangs a second too long followed by a prompt that feels out of place.
Nothing major. Nothing they'd complain about. Nothing that shows up in your monthly dashboard. But that's the first crack.
The next day? A balance that loads inconsistently. A security step that feels clunky. A savings nudge that feels like an obstacle instead of an insight. Another crack. Another leak.
The customer doesn't call. They don't ask for help or stomp into a branch demanding better. They just quietly try another app “to see what it's like.” Then they start moving small transactions there. Then their recurring payments. Then their savings.
This isn't just attrition; it's a slow-motion betrayal. The customer may technically still be yours, their account open on paper… but they are already emotionally and digitally mortgaged to your competitor. You paid the cost to acquire them, only to hand them over without a fight.
And here's what makes these hairline cracks so dangerous: they're invisible in every dashboard you're currently watching. Your monthly active users look fine. Your account closures are stable. Your NPS score hasn't moved. But underneath those aggregate metrics, the structure is failing… one micro-moment at a time.
The collapse you see is just the final scene.
Four Cracks and a Flood
A few years ago I was in the market for a HELOC. I searched rates and the best one was from a financial institution about 30 minutes away. My wife and I set an appointment, took some time off from work and went to the branch. We filled out an application and opened an account. In short order we were approved and on our way. Easy peasy.
The next day I downloaded the digital banking app and logged in. I was immediately met with friction by way of an ad that I had to watch before I could see the dashboard. Once I made it through to the dashboard, it felt like I was transported to 2010. The UI was antiquated, but displayed the essentials.
The first thing I wanted to do was transfer some money from my “big bank.” I easily found the “Add External Account” option on the sidebar and clicked it. What happened next was baffling. I couldn't figure out how to add my external account. As a digital banking professional, I fancy myself pretty adept at navigating digital banking. But I just couldn't crack this one. No instructions, no messages to prompt me along. Nothing. I was forced to call customer service.
The nice woman on the phone politely told me I needed to come into the branch to finish adding my external accounts. I couldn't believe this. Having worked in fintech for more than a decade and intimately knowing the products that enable this task to happen seamlessly, within seconds (see Plaid, Yodlee, etc.), just blew me away.
What happened next? It took me a month to get back to that branch. Because, you know… work, kids… life. Their digital experience taught me… in less than five minutes… that doing business with them would always require more effort than it should.
- —That ad before the dashboard? First crack.
- —The 2010 UI? Second crack.
- —The external account dead end? Third crack.
- —The requirement to come back to the branch? That was water pouring through.
I was still technically their customer. But the relationship was already over. They just didn't know it yet. This isn't unique to that credit union. It's happening at institutions across the country, in moments so small they don't even register as problems.
Where the Cracks Form
The Three-Second Test
Every time a customer opens your app, they're running an unconscious calculation: Is this worth my time? If your balance takes more than three seconds to load, you failed the test. Not because three seconds is objectively long… but because every other app they use is faster.
They're not comparing you to other banks. They're comparing you to Instagram, Spotify, and Amazon. And in that comparison, a three-second delay feels like an eternity.
The Authentication Gauntlet
Security is non-negotiable. But ask yourself: how many steps does it take for a customer to simply check their balance? Open app. Face ID. Security question. Pin code. Another verification prompt because they're on a new device.
Each step is individually justifiable. Together, they're a crack that widens every time your customer decides it's “not worth it” to log in for a quick check.
The Invisible Dead Ends
A customer starts to set up a savings goal. The feature requires linking an external account. The linking process fails silently. No error message, no explanation, just… nothing happens. They try once more. Still nothing. They close the app and never try again.
You see “low feature adoption.” What you don't see is the five-star customer who just learned that trying new things in your app leads to frustration.
The Inconsistent Experience
Your customer tries to update their address on mobile. The form doesn't work properly, so they switch to desktop. Desktop has a completely different interface. They have to re-enter information. They finally get it done, but the experience taught them: this bank's digital experience is unpredictable.
Each of these moments is a hairline crack. Individually, they seem manageable. Together, they compound into structural failure.
The Compounding Effect
Here's what most institutions miss: these micro-moments don't exist in isolation. They compound. A customer has a clunky authentication experience on Monday. On Wednesday, a balance loads slowly. On Friday, a feature doesn't work as expected.
None of these moments alone would cause them to leave. But together? They're building a mental model: this bank doesn't prioritize my experience. And once that model forms, every subsequent interaction gets filtered through it. Even things that work get dismissed. Even improvements get overlooked.
Because trust isn't rebuilt in one great experience. It's rebuilt in a hundred unremarkable ones that just… work.
The customer who's already decided you're “fine but not great” isn't giving you credit for finally fixing the slow load time. They've already downloaded Chime, moved their direct deposit, and are now just waiting for a reason to fully switch.
By the time you fix them, the customer has already decided you're not worth the effort.
Sealing the Cracks Before They Spread
You can't eliminate every friction point in digital banking. But you can stop treating attrition like a mystery when the evidence is already in your data. The hairline cracks aren't invisible… you're just measuring the wrong things.
1. Audit the invisible dropoffs
Most institutions track completions: accounts opened, loans funded, features activated. But the cracks form in the abandonments you're not tracking:
- —How many customers start adding an external account but never finish?
- —How many begin a mobile deposit but close the app mid-flow?
- —How many tap “Transfer Money” but back out before confirming?
Action: this week, map your top five customer journeys and measure abandonment at every step. Not just “did they complete it?” but “where exactly did they quit?” The spot where 20% of customers drop off? That's your hairline crack. Fix that one point before you build another feature.
2. Track engagement decay, not just churn
By the time a customer closes their account, they left you emotionally months ago. The real warning signal is declining engagement:
- —The customer who logged in 25 times last month but only 8 times this month.
- —The feature that had 60% adoption six months ago and 35% today.
- —The customer who used to transfer money weekly but hasn't in 30 days.
Action: build a simple dashboard that flags customers whose login frequency drops by 50% or more over 60 days. Don't wait for them to close their account… reach out when they start pulling away. That quiet withdrawal? That's water seeping through. Intervene before the structure fails.
3. Benchmark against the apps they actually use
Your customers aren't comparing you to the credit union down the street. They're comparing you to Venmo, Cash App, and Apple Pay. Action: download Chime, SoFi, and Cash App. Time how long it takes to open an account, add an external bank, transfer money, and check a balance after logging in.
Now time your own flows. If you're 2x slower, that's not acceptable. If you're 3x slower, that's a structural crack waiting to spread. Speed isn't a feature. It's table stakes. And right now, you're probably losing without knowing it.
The institutions that win won't be the ones who analyze their failures better. They'll be the ones who see the cracks forming and intervene before failure becomes inevitable.
The Foundation That Prevents Fractures
These interventions reveal where the cracks are forming. But revelation without infrastructure is just expensive awareness. To actually prevent hairline cracks from becoming silent attrition, you need to build differently—not just measure better. The institutions that stop losing customers in micro-moments share three foundational capabilities.
Real-time behavioral intelligence
Traditional banking analytics tell you what happened last quarter. By then, the customer is already using another app for their primary transactions. You need a system that flags behavioral changes as they happen:
- —Login frequency declining week-over-week.
- —Features tried once, then abandoned.
- —Customers comparing your rates on your own website but not applying.
This isn't “better reporting.” It's an early warning system that detects stress before it becomes failure. The engineer at the dam didn't wait for quarterly inspections—she walked the base every single day. Your platform should do the same.
Friction elimination as a core capability
Most institutions approach digital banking by asking: “What features should we add?” The institutions preventing hairline cracks ask: “What friction can we remove?” Every unnecessary form field is a crack point. Every redundant security step is pressure building. Every “come back later to finish” is water seeping through.
Your platform shouldn't just enable digital account opening—it should make it so seamless that customers forget they're doing business with a bank. Pre-filled data. Intelligent identity verification. One-click external account linking. If your onboarding takes more than five minutes, you're not competing. You're teaching customers that doing business with you requires patience they don't have.
Intervention automation, not just detection
Seeing the cracks isn't enough. You need the ability to act on what you see—automatically, intelligently, and at scale. When a customer's engagement drops by 50%, does your system:
- —Automatically trigger a personalized re-engagement message?
- —Route them to a specialist who can intervene?
- —Offer a timely, relevant feature that brings them back?
Or does it just add them to a report that someone might review next month? The difference between those two responses is the difference between preventing attrition and explaining it. Your platform should close the loop: detect the behavioral signal, predict the risk, and trigger the intervention—without waiting for a human to notice.
Before It's Too Late
The customer who's leaving you isn't doing it today. They did it three months ago, one micro-moment at a time. The hairline crack you're ignoring this quarter becomes the exodus you're explaining to the board next year.
In digital banking, there is no “too small to matter.” There's only “too late to fix.”
The engineer whispered to herself: this is how it starts. Your customers are whispering something too: this is how it ends. The only question is whether you're paying attention.